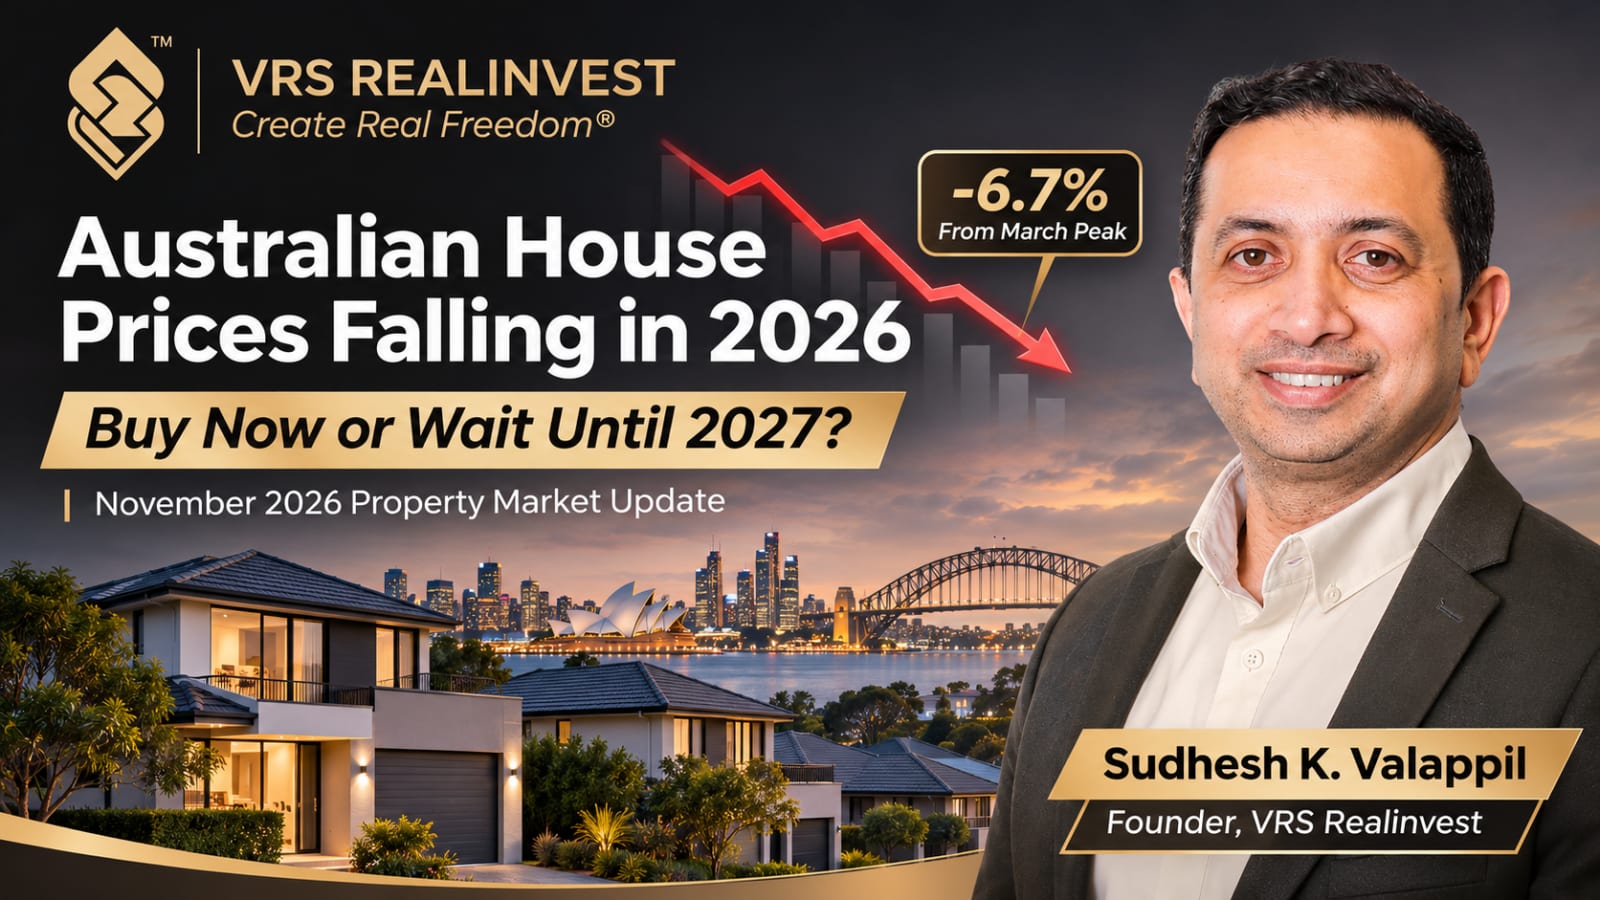
Australian House Prices Falling in 2026: Should You Buy Now or Wait Until 2027?
Australia's property market is experiencing one of its most significant downturns in recent decades.
According to Cotality's latest Home Value Index, published in November 2026, Australian property values declined by 1.2% during October, recording their seventh consecutive month of falling prices.
National home values have now fallen approximately 6.7% from their March 2026 peak, equivalent to around $63,400 in the value of the median Australian dwelling.
At the same time, the Reserve Bank of Australia increased the official cash rate to 4.85% on 3 November 2026, adding further pressure to borrowing capacity and mortgage affordability.
For Australian property buyers, this raises an important question:
Should you take advantage of falling property prices and buy now, or wait until 2027?
Let's examine the latest Australian property market conditions, what is driving house prices lower and how buyers can approach the current market.
1. What Is Happening to Australian House Prices in November 2026?
Australian property prices have been declining since March 2026.
The latest Cotality figures show:
National dwelling values declined by 1.2% in October 2026.
Property values have fallen for seven consecutive months.
National dwelling values are approximately 6.7% below their March peak.
Combined capital city values have declined approximately 8.1% over seven months.
The national median dwelling value is approximately $884,855.
The pace of the downturn is significant by historical standards.
However, it is important to understand that Australia's housing market is not one uniform market.
Different cities, suburbs and property types are experiencing different levels of price pressure.
For property buyers and investors, these differences matter more than simply looking at national averages.
2. Why Are Australian Property Prices Falling?
Several factors are contributing to the current property market downturn.
Higher Interest Rates
Interest rates have increased throughout 2026.
The RBA's November decision brought the official cash rate to 4.85%, the highest level since 2008.
Higher interest rates increase mortgage costs and generally reduce the amount buyers can borrow.
When borrowing capacity decreases, property demand can weaken.
Reduced Buyer Confidence
Many buyers are concerned about interest rates, economic uncertainty and the possibility of further property price declines.
Instead of making a purchasing decision, some are choosing to wait.
When fewer buyers compete for available properties, sellers may need to become more flexible with their asking prices.
Affordability Challenges
Even though house prices have fallen, properties remain expensive relative to many household incomes.
Higher mortgage repayments and living expenses continue to affect affordability.
A lower property purchase price does not automatically make a home affordable if financing costs remain high.
Changing Investor Demand
Higher holding costs and changes to property investment taxation can influence investor demand.
Some investors may postpone new purchases, while others may reassess properties that are generating negative cash flow.
These factors can create additional pressure in certain property markets.
3. Which Australian Property Markets Are Experiencing Price Declines?
The downturn has affected several major Australian capital cities, including Sydney, Melbourne, Brisbane, Perth and Adelaide.
Recent Cotality reporting indicates that Brisbane and Perth experienced particularly notable declines during October.
However, property performance can vary significantly within each city.
For example, one suburb may experience declining buyer demand while another may retain stronger demand because of employment opportunities, transport connections, schools and limited housing supply.
This means buyers should investigate:
Suburb-level property price trends.
Recent comparable sales.
Average days on market.
The number of properties available for sale.
Rental demand and vacancy rates.
Local employment and population trends.
Future housing supply.
An investment decision should be based on the fundamentals of the individual property and location, not just the national market direction.
4. Does Falling Property Prices Mean Buyers Have More Negotiating Power?
In some markets, yes.
When property prices are increasing rapidly, buyers may face intense competition.
Properties can sell quickly, and purchasers sometimes feel pressured to offer more than their planned budget.
During a slower property market, the balance between buyers and sellers can change.
Some vendors may become more willing to negotiate, particularly if they have already purchased another home, need to relocate or have experienced a lengthy selling period.
For financially prepared buyers, the current market may offer:
Reduced competition for selected properties.
Greater flexibility during price negotiations.
More opportunities to conduct due diligence.
Additional time to compare properties.
Potential opportunities to purchase below the original asking price.
However, not every seller is motivated, and not every property represents good value.
The objective should be to purchase a suitable property at a fair, evidence-based price rather than simply securing the largest advertised discount.
5. Should First-Home Buyers Buy Property Now or Wait Until 2027?
This is one of the biggest questions facing first-home buyers in Australia.
Some buyers are waiting because they believe house prices will continue falling.
Others are waiting for interest rates to decrease.
Both strategies involve uncertainty.
For example, if property prices decline further, waiting may result in a lower purchase price.
However, if competition increases or interest rates change, the financial outcome could be different.
An Example: Buying a $700,000 Property
Imagine you are planning to purchase a property worth $700,000.
If the price falls by another 5%, the purchase price would become $665,000.
That represents a difference of $35,000.
But purchasing at the lower price only creates a financial advantage if the property remains suitable, financing is affordable and other ownership costs are considered.
You must also consider what happens to your borrowing capacity and mortgage repayments during the waiting period.
Trying to predict the exact bottom of the property market is extremely difficult.
Instead, ask yourself:
Do I have a stable income?
Have I saved an adequate deposit and cash reserve?
Can I comfortably afford the repayments?
Am I purchasing for long-term ownership?
Have I researched the property and local market?
If you are financially prepared, it may be worth exploring available opportunities.
If your financial position is uncertain, strengthening your finances before purchasing may be the wiser decision.
6. Is 2026 a Good Time to Buy an Investment Property in Australia?
For property investors, declining prices can create opportunities, but careful research is essential.
An investment property must be assessed on more than its purchase price.
Consider a property that previously sold for $600,000 and is now available for $560,000.
The lower price may look attractive.
However, before purchasing, you should investigate whether the suburb has sustainable rental demand, stable employment opportunities and long-term growth prospects.
You should also check the property's condition and expected holding costs.
Five Factors Property Investors Should Consider
1. Rental Demand
Are people actively looking for rental accommodation in the suburb?
2. Vacancy Rates
A market with low rental vacancy may support stronger rental demand, although vacancy rates can change.
3. Cash Flow
Will the rental income adequately support mortgage repayments, council rates, insurance, management fees and maintenance?
4. Capital Growth Potential
Does the location have long-term demand supported by employment, infrastructure and population trends?
5. Risk Management
Can you continue holding the property if interest rates rise, rental income falls or unexpected repairs are required?
Remember that property values can continue declining after purchase.
There is no guarantee that a discounted property will increase in value within a particular period.
7. Why Buying in the Right Location Matters More Than Ever
One of the biggest mistakes property investors make is selecting a location based only on affordability.
For example, a buyer may find a property priced below $400,000 and assume it represents a good investment.
But a low purchase price does not automatically mean strong investment performance.
Some locations may have weak employment conditions, declining populations or limited rental demand.
Other locations may benefit from growing industries, transport access, infrastructure and diverse employment opportunities.
When researching a suburb, buyers should understand:
Population and employment trends.
The local rental market.
Future development and housing supply.
Historical property market performance.
Local amenities and infrastructure.
The balance between investors and owner-occupiers.
Good property research involves understanding why people want to live in a particular location and whether that demand is sustainable.
8. Will Australian House Prices Continue Falling in 2027?
Nobody can predict Australian property prices with certainty.
The direction of the market in 2027 will depend on several factors.
These include future RBA decisions, inflation, unemployment, mortgage affordability, consumer confidence and housing supply.
If interest rates remain elevated for longer, borrowing capacity and buyer demand may remain under pressure.
If interest rates eventually decrease, some buyers may return to the market.
However, lower rates do not guarantee rising property prices, particularly if employment or broader economic conditions weaken.
This is why buyers should avoid relying entirely on property price forecasts.
A sound investment strategy should be capable of managing different market scenarios.
9. The Biggest Mistake Buyers Make During a Property Market Downturn
One common mistake is making decisions entirely based on market headlines.
When property prices increase, buyers may worry about missing out.
When prices decrease, those same buyers may become afraid of purchasing.
This can result in years of indecision.
But purchasing without adequate research is equally dangerous.
The better approach is to establish a clear property buying strategy.
Understand your budget, your investment goals, your acceptable level of risk and the type of property that meets your needs.
A market downturn should encourage careful research and financial discipline.
It should not encourage rushed purchases simply because advertised prices have fallen.
10. How Can a Buyer's Agent Help in a Falling Property Market?
Purchasing property during uncertain market conditions requires careful property selection and negotiation.
An experienced buyer's agent can help buyers research suitable locations, assess property values and evaluate potential risks.
At VRS Realinvest, we help busy Australian professionals make informed property decisions based on their financial objectives and individual circumstances.
Our services include:
Property investment strategy support.
Suburb and location research.
Property shortlisting.
Comparable sales analysis.
Price negotiation.
Property purchasing coordination.
Our approach focuses on identifying suitable opportunities rather than purchasing a property simply because it appears inexpensive.
The objective is to help clients make informed decisions that support their long-term property ownership and wealth-building goals.
Final Thoughts: Should You Buy Now or Wait Until 2027?
Australian property prices are declining, interest rates are elevated and many buyers are uncertain about what will happen next.
These conditions create challenges, but they may also create opportunities for those who are financially prepared.
The decision to buy should not depend entirely on whether property prices fall another 2%, 5% or 10%.
Instead, focus on your financial readiness, your ability to manage mortgage repayments, the quality of the property and your long-term goals.
You cannot control interest rates or the property market. But you can control the quality of your research, your financial planning and the decisions you make.
Ready to Explore Property Opportunities in Australia?
Are you planning to buy your first investment property or expand your existing property portfolio?
At VRS Realinvest, we help busy professionals understand the Australian property market and identify properties aligned with their investment goals.
If you are unsure whether to buy now or wait, consider booking a one-on-one Property Strategy Session to discuss your objectives, budget and next steps.
Visit: https://vrsrealinvest.com.au
VRS Realinvest — Create Real Freedom®
Sources
Cotality — Australian Housing Market Updates: https://www.cotality.com/au/newsroom
Reserve Bank of Australia — November 2026 Monetary Policy Decision: https://www.rba.gov.au/media-releases/2026/mr-26-30.html
Reserve Bank of Australia — November 2026 Economic Conditions: https://www.rba.gov.au/publications/smp/2026/nov/economic-conditions.html
Disclaimer: This article provides general information only and does not constitute personal financial, investment, taxation or credit advice. Property prices can rise or fall. Individual circumstances vary, and readers should obtain appropriate professional advice before making financial decisions.